A US state regulator claims A-CAP’s football clubs are still exposed to 777 Partners and received loans that were wrongly reported.
By Paul Brown and Philippe Auclair
Fans of the football clubs in the 777 Partners portfolio could have been forgiven for thinking their troubles were over when the Miami investment firm collapsed and new custodians were found to guide them into the future.
Instead, Standard de Liège, Red Star Paris, Genoa CFC, Sevilla, Vasco da Gama and Hertha Berlin are embroiled in a new crisis driven by the firm which took over those ownership stakes.
In June 2025, Josimar reported how A-CAP, a lender to 777 Partners, foreclosed on a loan to the company and then seized all of the shares in these clubs as the preferred bidder at auction.*
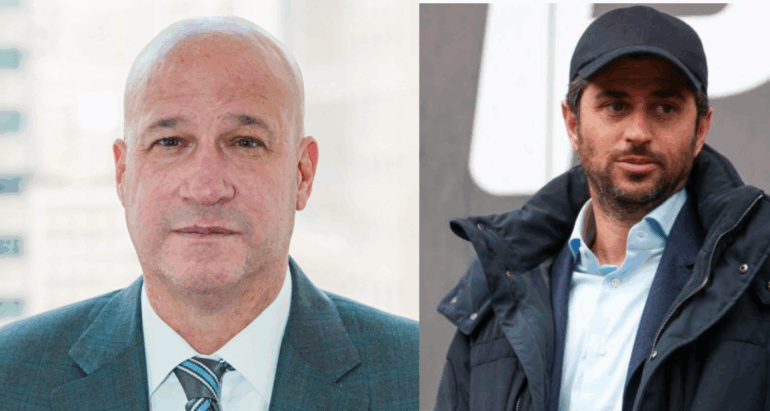
A-CAP operates five life insurance companies in the USA, where one state regulator now claims continued exposure to 777 Partners has endangered policyholders. A-CAP denies this. Kenny King, A-CAP’s owner and operator, has been accused in civil litigation of being the “puppeteer” behind the “fraudulent scheme” run by 777 Partners. He denies this.
Two of A-CAP’s five insurers – Atlantic Coast Life and its subsidiary, Southern Atlantic Re – are based in South Carolina, where the state’s insurance regulator has petitioned a judge for emergency intervention, stating that the two firms are in a “financially hazardous” condition as a result of ongoing exposure to 777 Partners, which could top $1.3 billion according to documents seen by Josimar.
In March of this year, under pressure to sell off assets, A-CAP announced an agreement for Internazionale Milano owners Oaktree to purchase Atlantic Coast Life. The deal has yet to close. Now, the South Carolina Department of Insurance wants to seize both Atlantic Coast Life and Southern Atlantic Re and place them into rehabilitation, a process which could ultimately lead to their liquidation, putting future funding for the football clubs at risk.
Affiliated assets
At the heart of the dispute is the entity which ended up holding all the shares in the clubs, and which has been used to continue funding them – Caboose Holdings LLC.
Caboose appears in statutory financials filed by A-CAP’s insurers, and South Carolina warns that therefore the insurers have exposure to “European professional soccer clubs that have never turned an operational profit,” citing them as examples of “distressed or insolvent companies” in which the insurers are invested.
777 Partners held the shares in a subsidiary called Nutmeg Acquisition LLC. Josimar has reviewed documents from 777’s recent bankruptcy filing in Texas which show that Nutmeg Acquisition’s assets, simply listed as “international football clubs”, were transferred in return for the “satisfaction of $157m of debt”. In other words, rather than buying the clubs’ shares, A-CAP took ownership in return for writing off $157m of the money it was owed by 777 Partners.
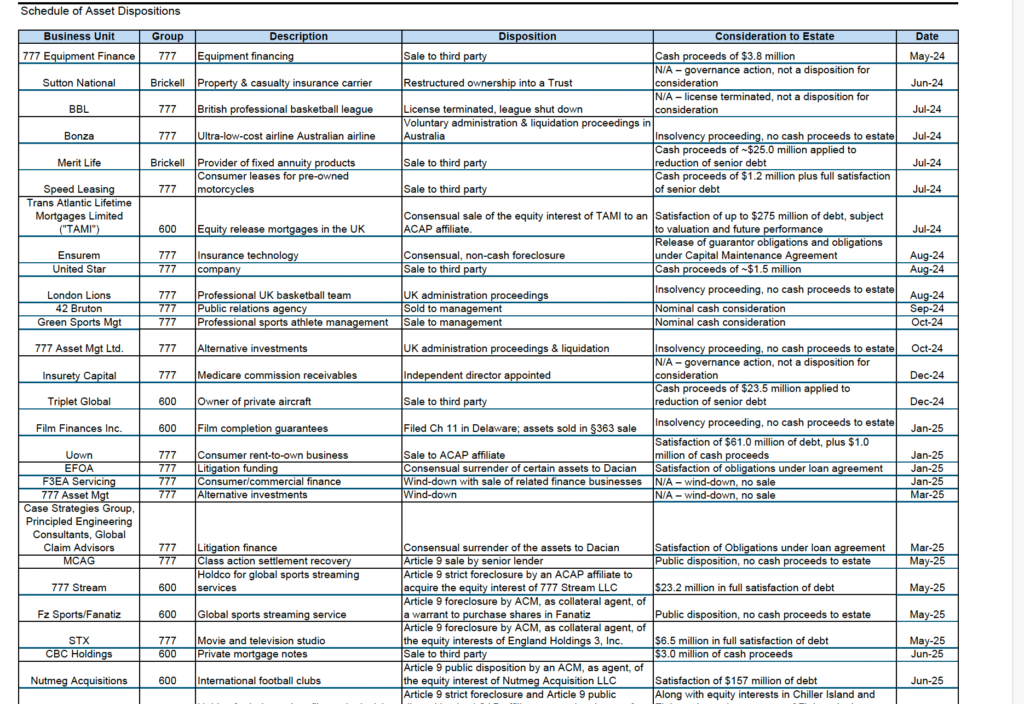
A-CAP insurers’ statutory filings reveal a corporate pyramid: Nutmeg Acquisition LLC is directly controlled by Nutmeg Intermediate LLC, which sits under Caboose Holdings LLC. Caboose is in turn held by Advantage Capital Holdings LLC, the entity ultimately controlled by A-CAP’s chief executive, Kenny King.
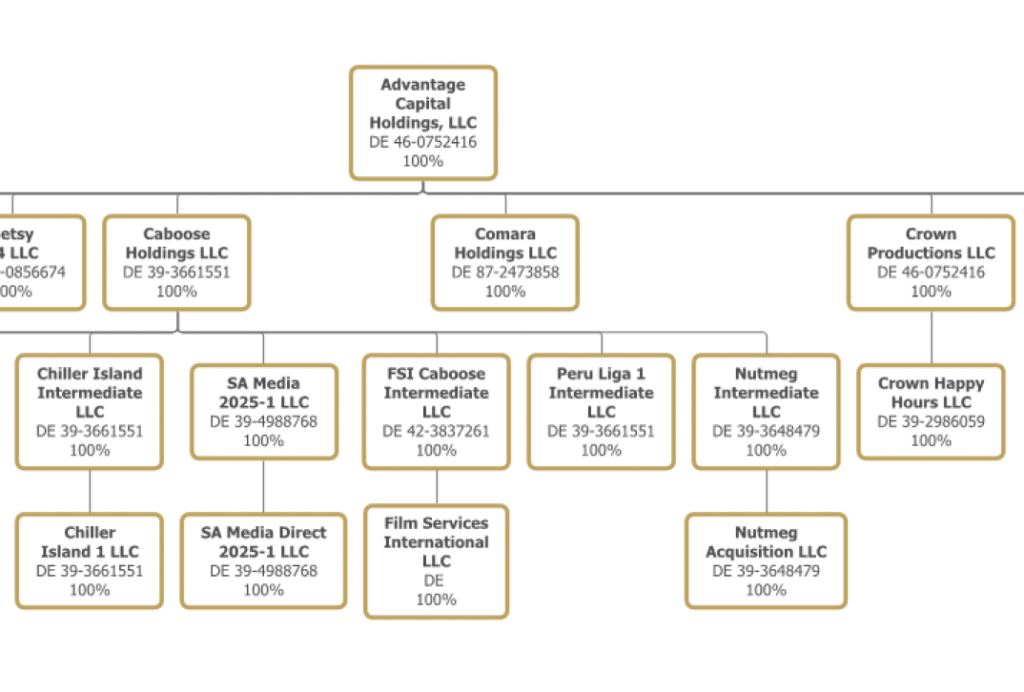
But South Carolina alleges that the assets held in Caboose have been “improperly reported” as unaffiliated when in actual fact they are now “investments in a single person and its affiliates – namely, affiliates of Mr. King and A-CAP.” This also makes them affiliates of the two A-CAP insurers which South Carolina monitors – Atlantic Coast Life and Southern Atlantic Re.
It is important to note here that for a lender like A-CAP, loans are considered assets on the balance sheet – and the assets being referred to here by the regulator are the loans held in Caboose, some of which were used to help fund the football clubs.
South Carolina claims that if these loans – several of which “are nonperforming or have defaulted” – had been properly reported as affiliated, it would have pushed Atlantic Coast Life over the statutory limit for such investments by more than $150m, a calculation the regulator admits may even be understated. Proper reporting, according to the regulator, would force Atlantic Coast Life to disclose a negative surplus.
South Carolina contends that the financial position of the insurers is therefore “hazardous”, because of the “high concentration of investments in entities under the common control or ownership of Mr. King and A-CAP, which constitute investments in a single person and its affiliates.” South Carolina also claims “it is unclear what assets, if any” have been pledged as security for the loans held in Caboose. The state questions whether these assets are valuable or liquid enough to meet the insurers’ obligations to policyholders seeking withdrawals or payments.
Opposing those findings, A-CAP filed a motion to dismiss the regulator’s petition, claiming the department “fails to state facts sufficient to constitute a cause of action.” A-CAP also claims the Court of Common Pleas for the Fifth Judicial Circuit in Richland County, where South Carolina filed its petition, “lacks jurisdiction.” A-CAP later filed asking the court for “an immediate and permanent injunction” preventing the department from making public any more “confidential regulatory information”, highlighting that the petition fails to identify “a single policyholder claim Atlantic Coast failed to pay” and accusing the regulator of violating its rights and leaking vital company secrets. The case was designated “complex” and assigned to a judge.
A spokesman for A-CAP told Josimar: “Atlantic Coast Life and Southern Atlantic Re strongly dispute the South Carolina Department of Insurance’s petition for rehabilitation. The petition is not an adjudication that either company should be placed into rehabilitation, and no rehabilitation order has been entered. The companies continue to pay claims and service their policyholder obligations.
“Since Atlantic Coast Life and Southern Atlantic Re filed their lawsuit, the regulatory posture has changed. The South Carolina Department of Insurance has agreed in principle with Atlantic Coast Life and Southern Atlantic Re to pause the pending litigation and proceed to mediation. The parties intend to use that process to pursue a comprehensive resolution of their disputes and address pending regulatory matters.
“The Department’s agreement to mediate underscores that these issues remain contested and capable of resolution.”
Josimar understands that at the time of writing, no such mediation has been agreed to in practice, and that should the parties subsequently enter mediation, no legally binding outcome would necessarily ensue.
Wider issues
Incorrect reporting of affiliated investments has become a problem in the insurance industry, including for Mark Walter of Guggenheim Partners. After a US Department of Justice probe, Walter’s insurers were forced to reclassify assets, creating a need for liquidity which has resulted in him agreeing to the sale of his stake in Chelsea and his ownership interest in the LA Lakers.
The DOJ also subpoenaed A-CAP executives in relation to an investigation into 777 Partners which resulted in criminal fraud indictments against the Miami firm’s co-founder, Josh Wander, and its CFO Damien Alfalla. Wander is due to go on trial in October. Alfalla pleaded guilty and is co-operating. According to information provided to South Carolina, A-CAP insist they were not participants in any aspect of the alleged fraud, and that they were instead “pure victim-witnesses”. However, the regulator concludes that regardless of the accuracy of that assertion, “A-CAP’s close relationship to the financial turmoil and alleged criminal activity of 777 imperils the investments in 777-related assets that are necessary for paying policyholders.”
That phrase “close relationship” is of particular note. In a webinar held on 27 February 2024 when concerns were raised by investors about the links between the two companies, King told those present that: “A-CAP and 777 are not affiliates by any definition. A-CAP is a lender to 777… There’s no affiliation relative to the two entities.” In addition, in May 2024, an A-CAP representative told the New York Times that “A-CAP serves as a lender to 777 – there are no ownership ties.”
But it appears that A-CAP and 777 Partners held ownership interests in each other. A recent filing in 777’s bankruptcy petition shows that in April 2026, in return for the “satisfaction of $12.7m of debt”, A-CAP carried out a “consensual redemption” or mutually-agreed buyback of “777 Partners’ equity interest in Advantage Capital Holdings”, the entity which now sits just above Caboose in A-CAP’s organisational chart. In addition, South Carolina’s petition confirms that a “preferred equity investment” in 777 Partners currently sits in an A-CAP entity called AAV. This corresponds with a request for information in discovery in a related lawsuit which references “A-CAP’s 2021 purchase of preferred equity from 777 Partners.”
South Carolina concludes that the A-CAP insurers it regulates have remaining exposure to 777 Partners “not limited to loans from A-CAP,” that they “still have substantial financial entanglement with the 777 companies,” and that these relationships “have not been fully disclosed to the Department.”
Groundhog Day
Regular readers of Josimar could be forgiven a feeling of deja vu, as this is far from the first time US state insurance regulators have gone after A-CAP. Eighteen months ago, Josimar reported how the Utah Insurance Department launched a similar petition stating that the three A-CAP insurers domiciled in the Mormon state were in a similarly hazardous financial condition owing to their exposure to 777 Partners and should be seized for rehabilitation. That petition alleged that King and other A-CAP employees “have directly and improperly benefitted from those investments” via management fees, a Miami condo, mortgage loans and “compensation paid directly to A-CAP”.
Following mediation, the two sides reached an out of court settlement. The details of the settlement were not made public but they allowed A-CAP to remain in control of the three insurers and avoid rehabilitation.
Going back even further, both Utah and South Carolina issued orders in December 2024 banning all five A-CAP insurers from writing any new insurance or annuity premiums due to mounting concerns over their finances. Utah then agreed to stay their order pending mediation, and the later settlement allowed the insurers to resume doing business. A-CAP appealed South Carolina’s order, and two months later an administrative law judge struck down the ban. Now the two sides are back in court.
Negative implications
In another blow to A-CAP two of its insurers – including Atlantic Coast Life – had their credit ratings downgraded for the second time this year on Tuesday. Ratings agency AM Best made that decision based on “increasing weakness in A-CAP Group’s balance sheet strength as well as its operating performance during the first half of 2026.”
The ratings remain “under review with negative implications”, AM Best said, a status which “also acknowledges the recent Rehabilitation Petition filed by the South Carolina Department of Insurance.”
Credit ratings are crucial for US life insurers because they measure a company’s financial strength – and its ability to pay policyholder claims as they become due.
The two companies downgraded are the only A-CAP insurers which issue policies directly to the general public and are thus vital to the group’s business. AM Best downgraded their Financial Strength Rating to C+, indicating only a “marginal” ability to meet their obligations. There are four ratings categories higher than that on the AM Best scale, and only two lower – “weak” and “poor”.
AM Best noted that the two insurers have been suffering a decline in capital for the last two years and that they are heavily invested in assets “not traditionally associated” with insurance companies. These include A-CAP’s investments in the football clubs.
AM Best also pointed to a concentration of investments in affiliated assets and “uncertainty” surrounding the completion of the Oaktree transaction, which would have been accompanied by an injection of fresh capital and a corporate restructuring.
A-CAP sued AM Best over a previous downgrade in 2024 and the two parties later reached a settlement.
An A-CAP spokesman told Josimar the firm disagreed with the latest downgrade, saying “it does not reflect A-CAP’s pending capital raise and corporate restructuring initiatives, which were acknowledged by AM Best and are continuing to develop.
“Sentinel Security Life and Atlantic Coast Life have been insurance companies for more than a century. Through their long and proud history they have served policyholders through generations of economic and market cycles and remain committed to employees and meeting obligations to policyholders throughout the United States.”
*In the case of Standard, A-CAP’s shares were later acquired by SDL Holding SRL, headed by the club’s CEO Giacomo Angelini. But A-CAP continued to fund the club via a revolving credit facility which still appears on the financial statements of its insurers and is mentioned in the Belgian football regulator’s 2026 club licensing report.